The Greater Pasadena 30-Day Market Report July 8 points to a market that is not frozen, not overheated, and not especially simple. In other words, a very real summer market.
Over the latest 30-day period, Greater Pasadena showed 387 total market actions, including 91 new listings, 124 active listings, 54 price reductions, 52 pending sales, and 108 sold properties.
Compared with the prior 30-day period, activity increased sharply in several important categories. That is the useful part. The market is still moving. But the way it is moving matters.
The latest 30-day Greater Pasadena snapshot.
| Category | Latest 30 Days |
|---|---|
| All Activity | 387 |
| Compass Private Exclusives | 0 |
| Coming Soon | 3 |
| New Listings | 91 |
| Active Listings | 124 |
| Back On Market | 3 |
| Price Increases | 4 |
| Price Reductions | 54 |
| Accepting Backup Offers | 44 |
| Pending | 52 |
| Hold | 13 |
| Withdrawn / Cancelled | 25 |
| Expired | 18 |
| Sold | 108 |
For this Greater Pasadena 30-Day Market Report July 8, the strongest local signal is not just one number. It is the relationship between new listings, active listings, price reductions, pending sales, and closed sales.
More homes came on the market. More homes were active. More homes went pending. But more sellers also reduced their prices.
That combination tells us buyers are still participating, but they are not giving every listing a free pass.
What changed from the prior 30 days?
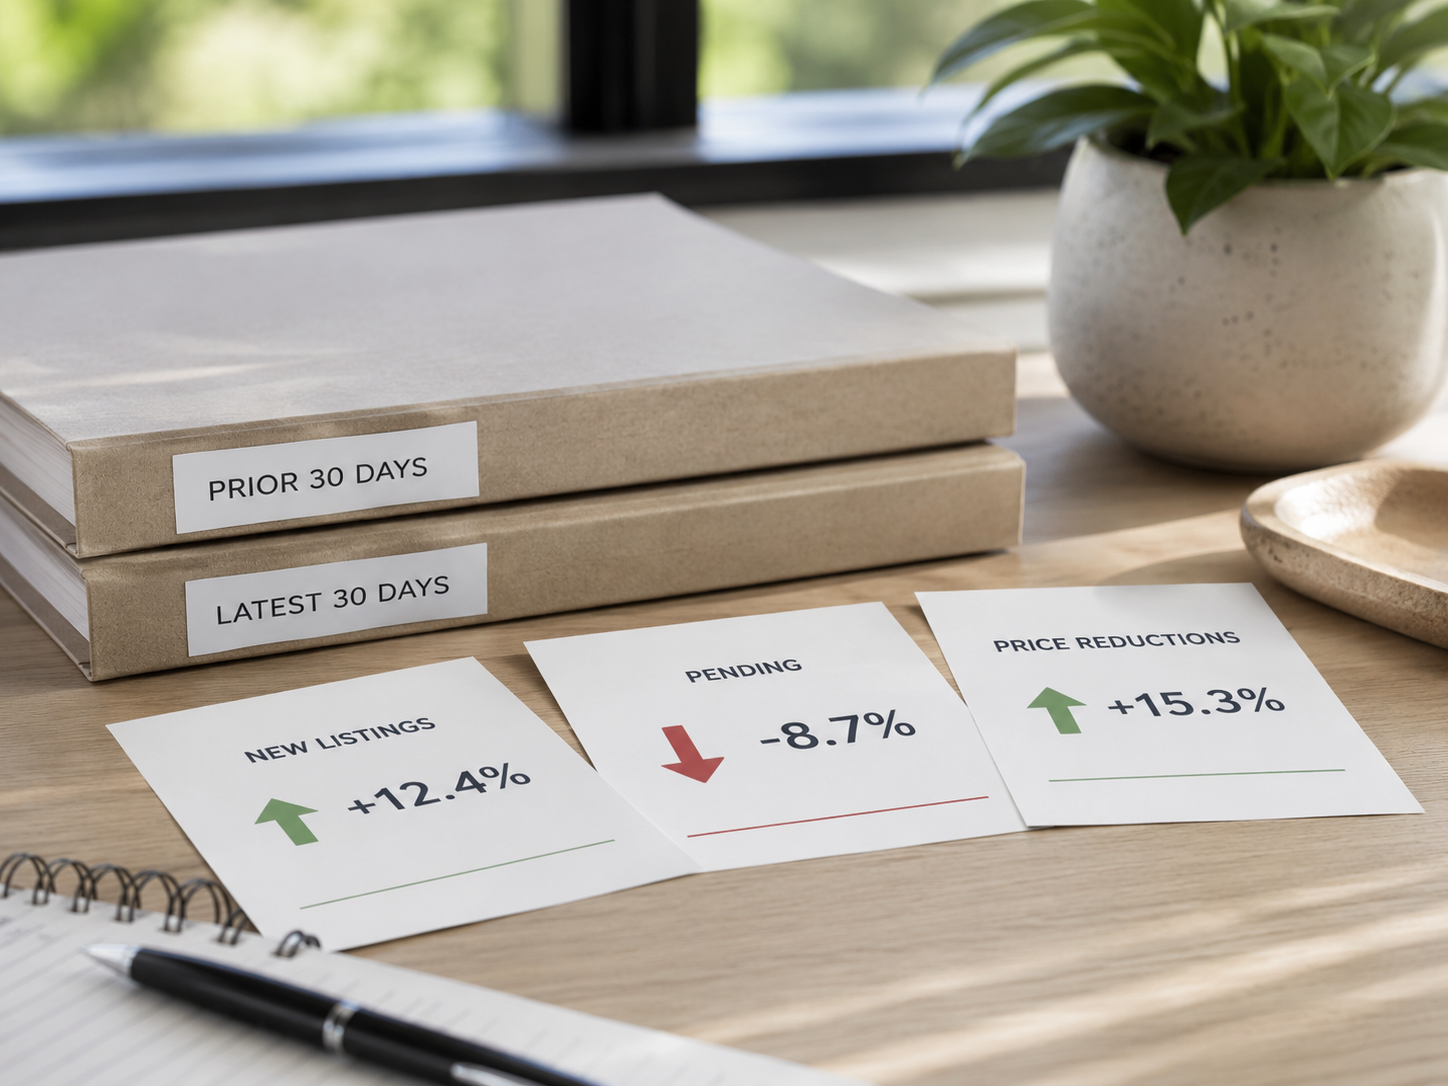
| Category | Prior 30 Days | Latest 30 Days | Change | % Change |
|---|---|---|---|---|
| All Activity | 238 | 387 | +149 | +62.6% |
| Compass Coming Soon | 1 | 3 | +2 | +200.0% |
| New Listings | 49 | 91 | +42 | +85.7% |
| Active Listings | 59 | 124 | +65 | +110.2% |
| Back On Market | 2 | 3 | +1 | +50.0% |
| Price Increases | 1 | 4 | +3 | +300.0% |
| Price Reductions | 39 | 54 | +15 | +38.5% |
| Accepting Backup Offers | 9 | 44 | +35 | +388.9% |
| Pending | 11 | 52 | +41 | +372.7% |
| Hold | 2 | 13 | +11 | +550.0% |
| Withdrawn / Cancelled | 29 | 25 | -4 | -13.8% |
| Expired | 13 | 18 | +5 | +38.5% |
| Sold | 114 | 108 | -6 | -5.3% |
Some of the percentage changes look dramatic because the prior 30-day base was small, especially in categories like Coming Soon, Price Increases, Hold, Accepting Backup Offers, and Pending. The most important signals are the larger categories: new listings, active listings, price reductions, pending sales, and sold properties.
The latest 30 days were much more active than the prior 30 days. New listings rose 85.7%, from 49 to 91. Active listings increased 110.2%, from 59 to 124. Pending sales climbed 372.7%, from 11 to 52.
That is not a sleepy market. But it is also not a market where sellers can name a number and wait for applause.
Price reductions increased 38.5%, from 39 to 54, while sold properties slipped 5.3%, from 114 to 108. That suggests stronger listing and pending activity has not fully turned into stronger closed-sale activity yet.
The market is active, but more selective.
The practical read from the Greater Pasadena 30-Day Market Report July 8 is this: buyers are still engaging, but they are becoming more careful.
Homes that are well priced, well prepared, and easy to understand are still getting attention. The jump in pending sales and accepting-backup-offer activity supports that. Buyers have not disappeared.
But the increase in active listings and price reductions shows that buyers are sorting more aggressively. A home that feels overpriced, underprepared, or poorly launched can start to feel stale faster than sellers expect.
That is especially important as we move deeper into summer. July is often when the market takes its foot off the gas. Spring listings begin to age, vacations interrupt buyer focus, and urgency can soften.
How the national picture fits.
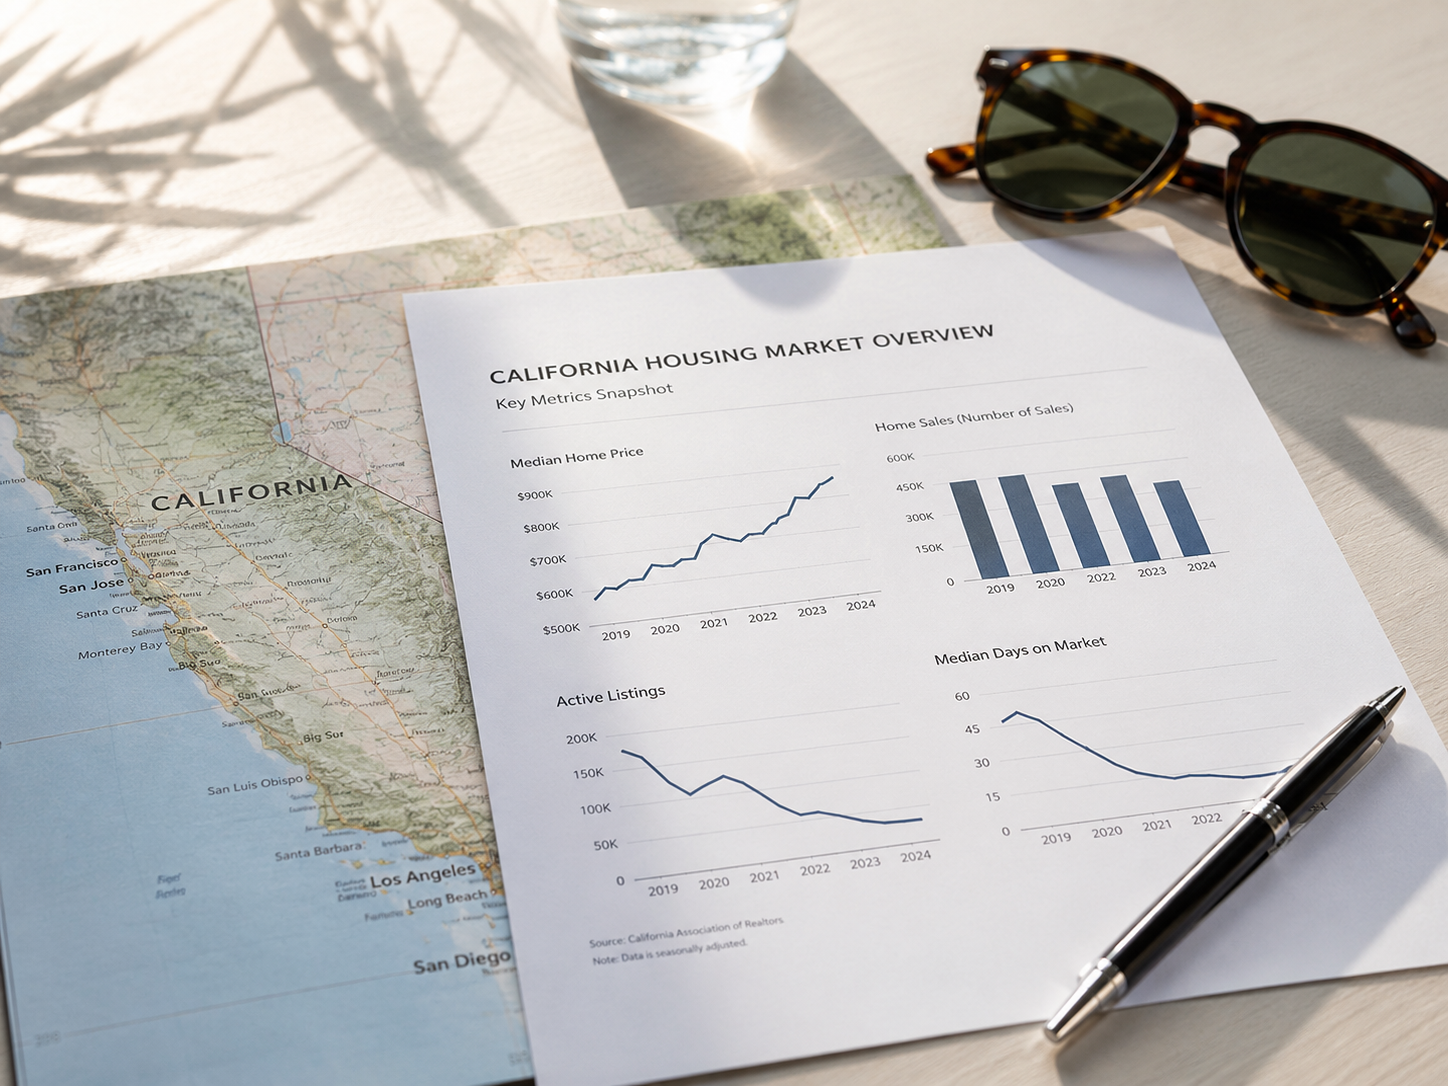
The national data points in a similar direction.
Realtor.com’s June 2026 Monthly Housing Trends Report described June as a steadier month for housing, with new listings up 2.4% year over year, pending sales rising for a seventh straight month, and median time on market holding at 53 days, the same as June 2025.
At the same time, Realtor.com reported that 18.8% of active listings had price reductions in June, up from May as part of the normal summer ramp.
That national pattern fits what we are seeing locally: activity is still present, but pricing discipline matters more.
Realtor.com also reported that national median list prices were down 2.5% year over year, with regional softness in the West. That does not mean every Greater Pasadena home is worth less. Local home values depend heavily on city, condition, architecture, lot, school district, setting, and price tier. But it does reinforce the larger point: sellers cannot rely on old momentum alone.
C.A.R.’s Market Minute adds another layer. Its June 29, 2026 update noted encouraging signs in housing and economic indicators, but also said elevated mortgage rates and cost-of-living pressures are likely to keep weighing on the market, with improvement in the second half of 2026 expected to be gradual.
Why cross-market demand still matters.
Greater Pasadena does not operate in a sealed glass box. Buyer demand can come from local move-up buyers, Los Angeles-area relocations, downsizers, families comparing school districts, and people moving between nearby communities.
That is why Realtor.com’s Cross-Market Demand Report is useful background. It tracks where out-of-market home shoppers are looking and where local shoppers are searching outside their own market.
For Greater Pasadena, this matters because demand may not always be obvious from local listing counts alone. A Pasadena buyer may also be comparing South Pasadena, Altadena, Sierra Madre, San Marino, La Cañada Flintridge, and parts of Los Angeles.
An out-of-area buyer may see Greater Pasadena as a lifestyle, school, architecture, or commute decision rather than just a price comparison.
What should we watch heading into July?
The Greater Pasadena 30-Day Market Report July 8 gives us three main things to monitor.
First, we should watch whether active listings keep growing faster than pending sales. More inventory gives buyers more choice. But if pending sales keep pace, the market may simply be more active rather than weaker.
Second, we should watch price reductions. Some summer price cuts are normal. But if reductions accelerate, that suggests more sellers overshot the market or missed the best pricing window.
Third, we should watch whether new listings pull back. Realtor.com made a similar point nationally, noting that July is when the market traditionally slows and that the key questions are whether homes start sitting longer, price cuts accelerate, and new listings pull back or flatten out.
The key is balance. A healthy market can have more listings and more price reductions. The question is whether demand keeps absorbing the homes that are properly priced and well presented.
What this means for sellers.
For sellers, the message is clear: do not treat July like April with warmer weather.
A successful launch now needs sharper preparation, more careful pricing, and a stronger first impression. Buyers may still act quickly on the right home, but they are less likely to chase a listing that feels ambitious without evidence.
The increase in price reductions does not mean sellers have lost control. It means the market is demanding better judgment upfront.
Before listing, sellers should ask:
- Does the price match the current competition?
- Does the home show well online and in person?
- Are there obvious objections that should be addressed before launch?
- Is the listing strategy built for today’s market, not last spring’s mood?
A good listing can still do well. A careless launch can get expensive.
What this means for buyers.
For buyers, the latest numbers are encouraging, but not permission to drift.
More active listings and more price reductions may create better opportunities, especially on homes that have been sitting or recently adjusted. But the rise in pending sales and accepting-backup-offer activity shows that good homes are still moving.
Buyers should be prepared to act when the right property appears, but also willing to ask better questions:
- Has the home been reduced?
- How long has it been active?
- Are there competing offers?
- Is the seller motivated, or simply testing the market?
- Is the list price realistic compared with recent activity?
The best buyer advantage in July may not be speed alone. It may be clarity.
The July takeaway.
The heart of the Greater Pasadena 30-Day Market Report July 8 is this: the market is more active, but also more selective.
Compared with the prior 30 days, Greater Pasadena saw more new listings, more active listings, more pending sales, and more backup-offer activity. That is a sign of movement. But the increase in price reductions and the slight dip in sold properties remind us that not every listing is being absorbed equally.
This is not a market for guessing. It is a strategy market.
For sellers, that means pricing and preparation before the public launch. For buyers, it means understanding where there may be negotiating room and where competition is still strong.
Use this Greater Pasadena 30-Day Market Report July 8 as a starting point, not a substitute for property-specific advice. The right strategy depends on the city, the home, the condition, the price range, and the timing.
Thinking about a move in Greater Pasadena?
Hem-young deFazio of The deFazio Experience at Compass helps buyers and sellers understand not just what the market is doing, but what it means for their next decision.
Call or text Hem-young at 626-825-5599 before you price a home, write an offer, or assume the market is moving the same way in every neighborhood.
The July market has opportunities, but it is not handing out easy answers. A clear plan can make the difference.